France proposes taxing gains when crypto becomes stablecoins
French MPs propose taxing gains on conversions into e-money stablecoins from 2027. The current private-investor flat rate is 31.4%; the measure remains under debate.
Listen to this articleListen
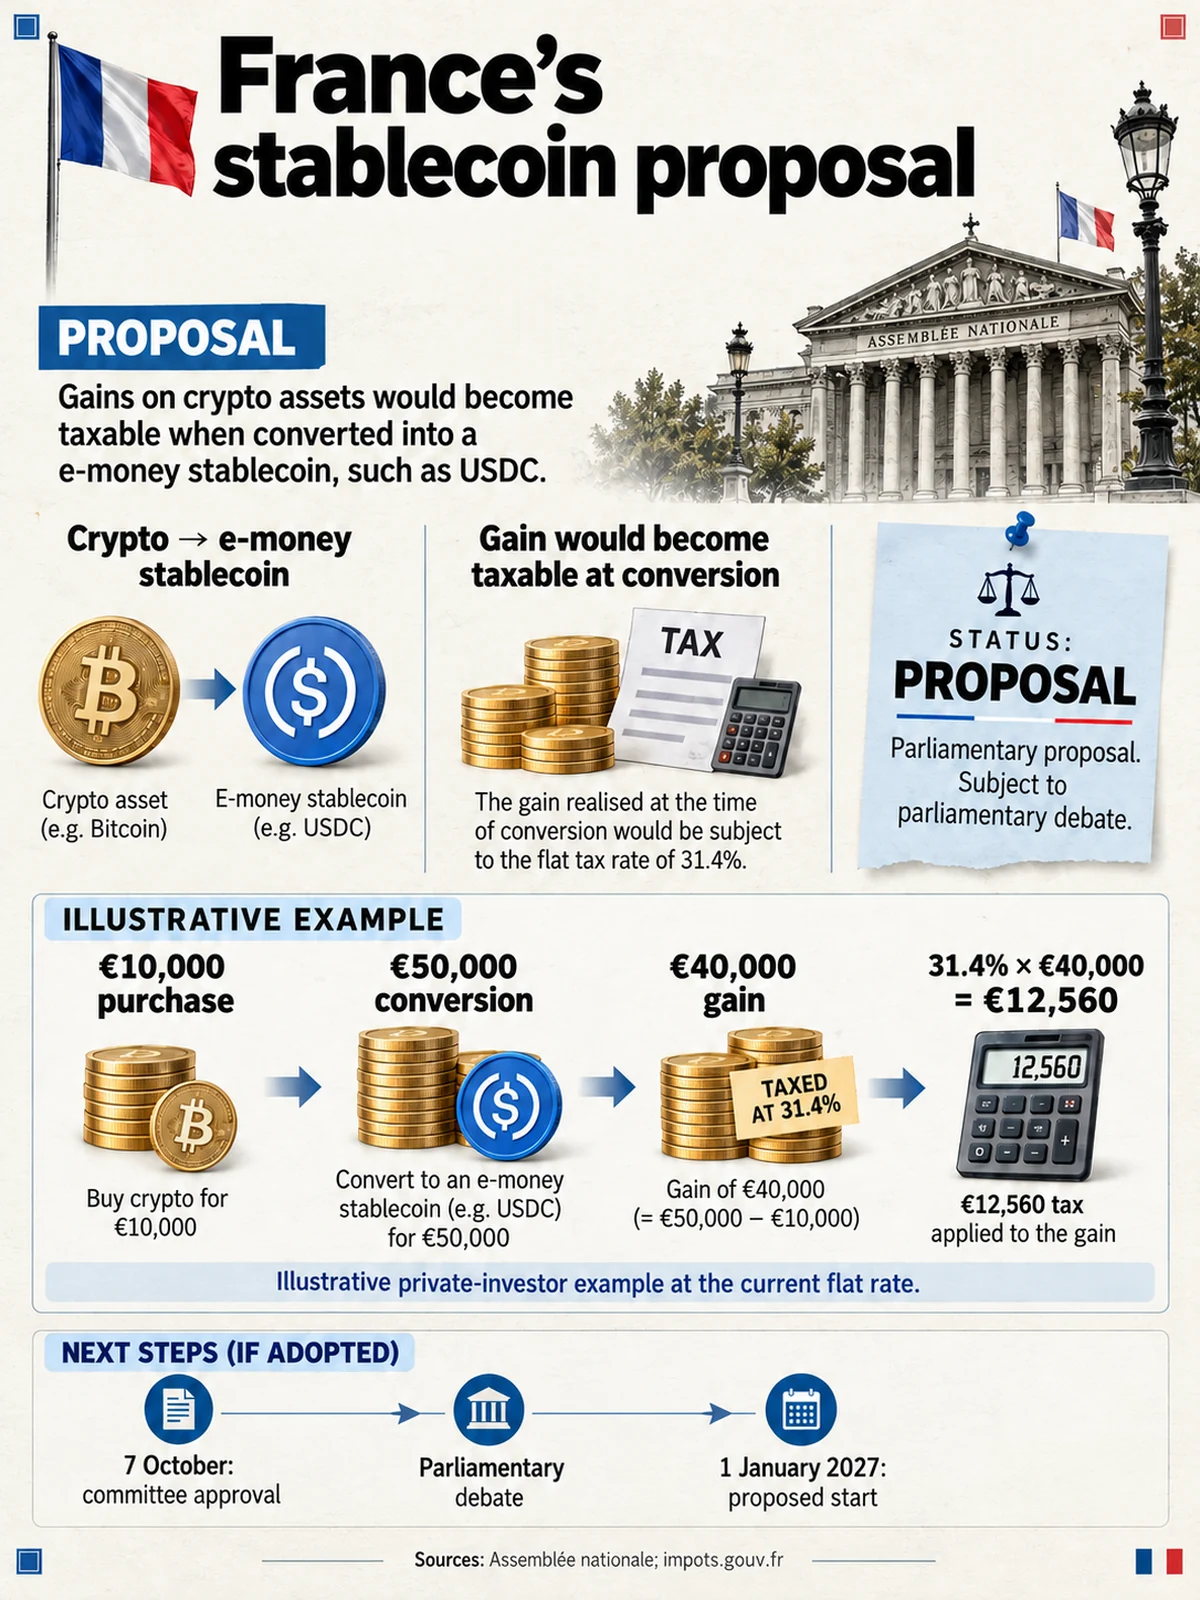
French MPs are proposing to tax gains when investors exchange cryptocurrencies for stablecoins linked to a single currency. The proposal would move the tax point forward to the conversion itself, using France’s existing private-investor tax framework.
The finance committee approved amendment I-CF1826 on 7 October. Its mechanism is now being debated in the full National Assembly through further amendments to the 2027 budget. The proposed start date is 1 January 2027.
The conversion would trigger the tax
The proposed change targets exchanges in which a holder receives an e-money token, the MiCA category for a crypto-asset seeking a stable value by reference to one official currency. The parliamentary wording uses that legal category, so the scope turns on the token’s characteristics.
For someone who bought a cryptocurrency and later exchanged it for a qualifying stablecoin, the conversion would crystallise a taxable gain. Moving from a volatile coin to a stablecoin often serves as a way to reduce market exposure while keeping funds available for another trade.
France’s tax authority currently describes a deferral for crypto-to-crypto exchanges without a cash adjustment. The proposal would change that treatment for the specified stablecoin conversions.
The 31.4% rate applies to a gain
The current flat rate for private-investor crypto gains is 31.4%, comprising 12.8% income tax and 18.6% social charges, according to the tax authority. The amendment changes the taxable event and cost calculation within that existing framework.
An illustrative purchase and conversion shows the distinction:
| Step | Illustrative amount |
|---|---|
| Cryptocurrency acquisition cost | €10,000 |
| Value received at stablecoin conversion | €50,000 |
| Realised gain | €40,000 |
| Tax at the current 31.4% flat rate | €12,560 |
This example assumes one acquisition, one conversion, the current flat rate and no deductible fees. Taxpayers can elect the progressive income-tax scale under the existing rules, while professional-style activity has its own treatment.
Critics see a cost for French platforms
MP Daniel Grenon has tabled a competing amendment to preserve deferral for these exchanges. His amendment I-3738, deposited on 10 October, says taxing reallocations within a crypto portfolio would increase reporting obligations and reduce the attractiveness of platforms established in France.
Tax lawyer Alexandre Lourimi, writing for ORWL, also argues that the change would tax a common portfolio-management step. His analysis, updated on 13 October, records the competing parliamentary amendments and the industry’s opposition.
Those concerns point to the competitiveness of domestic venues and the incentive to move activity elsewhere. The tax authority already requires French residents to declare digital-asset accounts held on foreign platforms. A platform’s location and a holder’s tax obligations are separate parts of the debate.
Parliament will decide the final treatment
The Assembly is considering both a taxable-conversion approach and an explicit continuation of deferral. Amendment I-3680 carries the conversion-tax mechanism into plenary debate. It also proposes calculating acquisition costs asset by asset, including a weighted-average purchase value for units of the same cryptocurrency.
The proposed rules give holders of assets acquired before 2027 a choice of transition methods for establishing their cost basis. The final budget text and its parliamentary passage will determine which treatment applies. For investors and platforms, the decision concerns when gains become taxable and how each transaction must be recorded.
Sources
- Assemblée nationale: committee amendment I-CF1826assemblee-nationale.fr
- Assemblée nationale: amendment I-3680 for plenary debateassemblee-nationale.fr
- Assemblée nationale: opposing amendment I-3738assemblee-nationale.fr
- French tax authority: private-investor crypto gainsimpots.gouv.fr
- ORWL: stablecoin conversion tax analysis, updated 13 Octoberorwl.fr